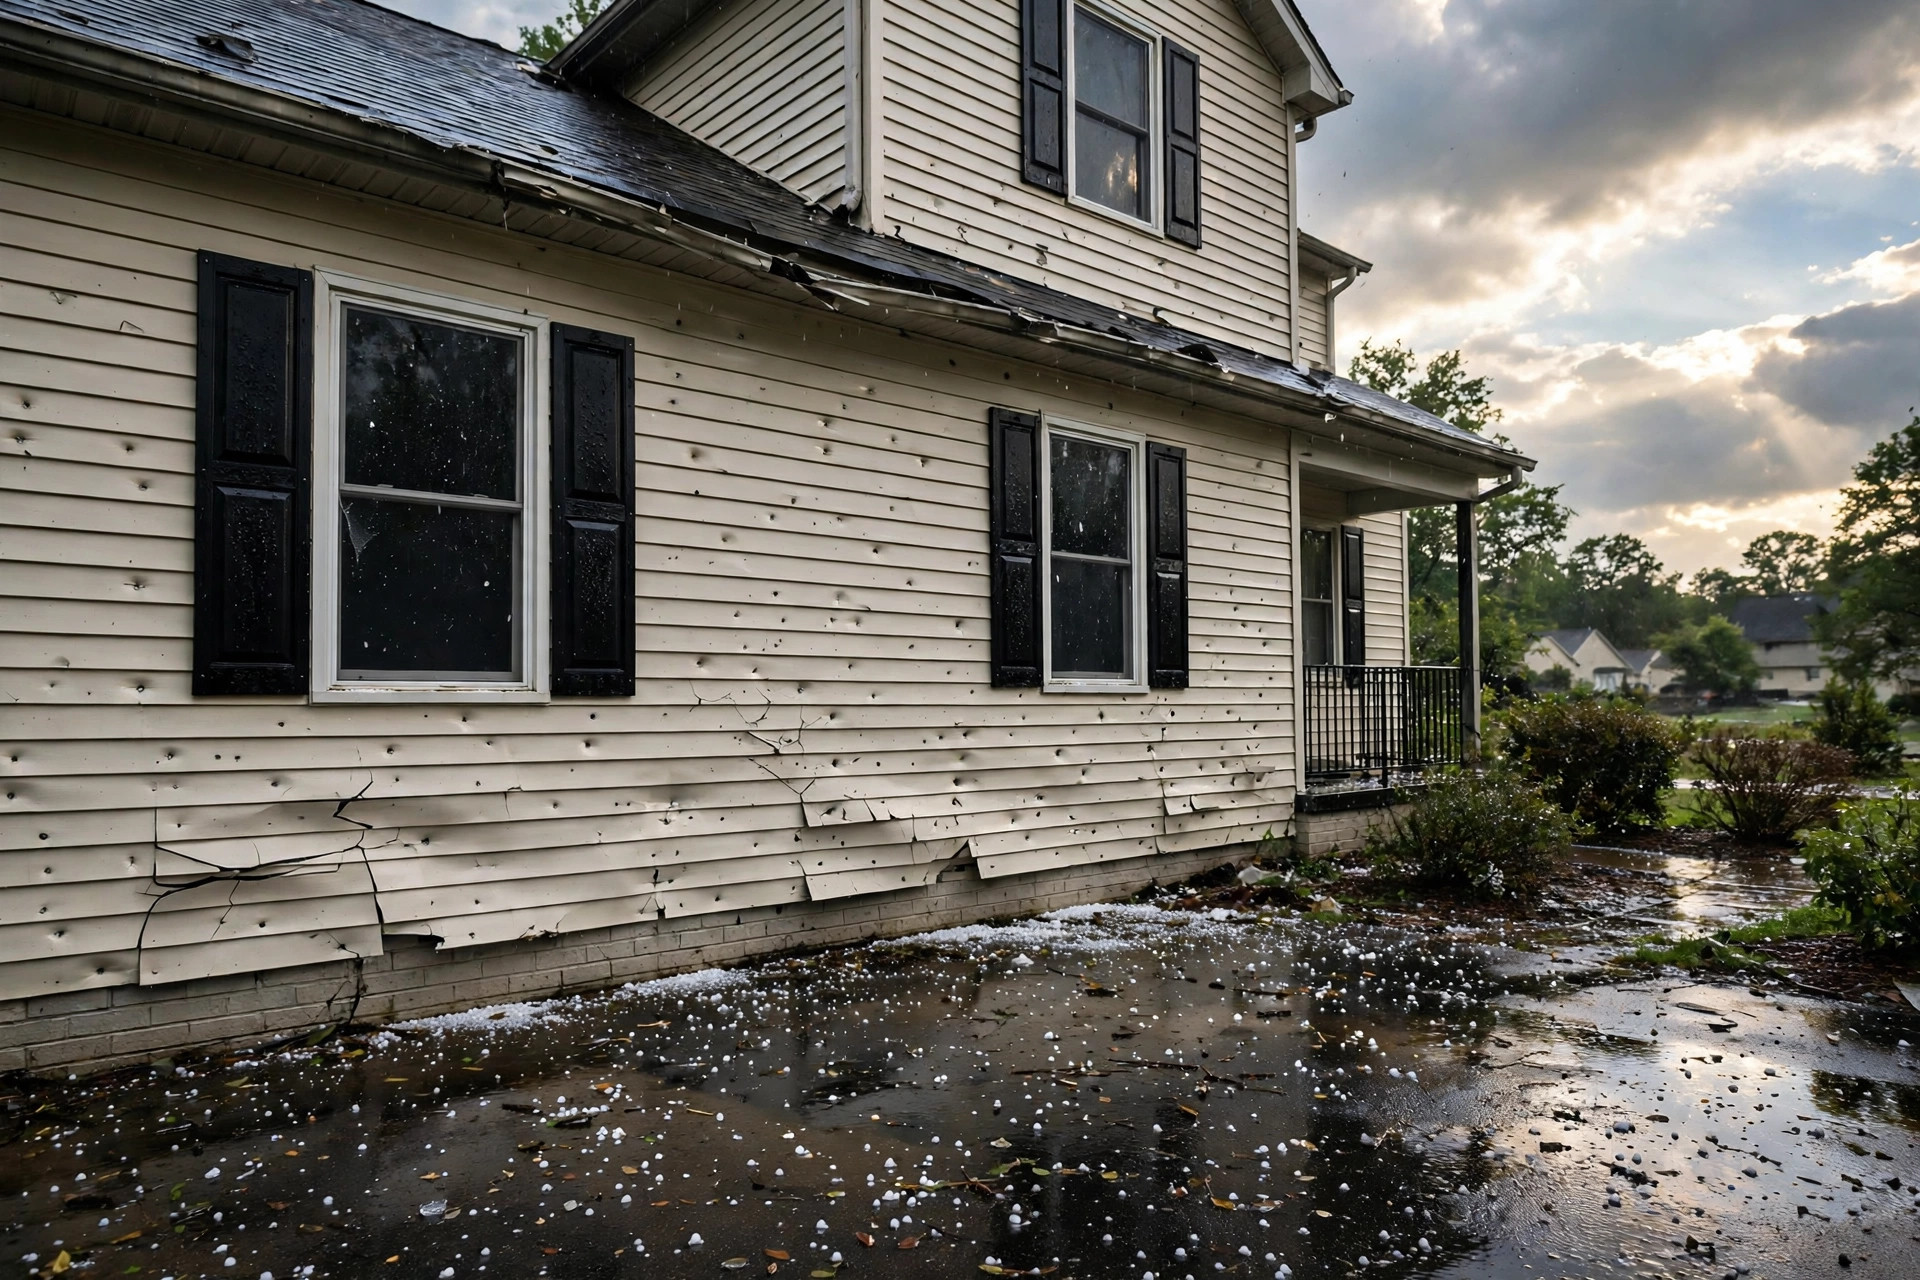
If a storm damages your siding, start by documenting the damage with photos, review your homeowner's policy dwelling coverage, and file your claim promptly. Insurers typically cover sudden, accidental damage — like hail or wind — but not wear and tear or pre-existing deterioration.
What Is Usually Covered
Most standard homeowner's policies cover sudden and accidental damage to siding from named perils such as hail, windstorms, and falling trees. What is generally not covered: gradual wear, fading, rot from long-term neglect, insect damage, and faulty installation. Every policy differs, so your declarations page and exclusions section are the real authority — read them before you call the insurer.
One common gray area is matching. If only one wall is damaged but the replacement siding does not match the rest, some policies address matching while others do not. Note the issue early and ask your adjuster how your policy handles it.
Document Everything First
Before any cleanup or temporary repair, photograph and video the damage from multiple angles, including wide shots showing the location on the house and close-ups of dents, cracks, and missing pieces. Note the date and cause if known — for example, the hailstorm on a specific evening. Keep any damaged pieces you can safely collect.
If water is entering the home, make reasonable temporary repairs (tarping, for instance) to prevent further damage — insurers expect this, and failing to mitigate can reduce your payout. Save receipts for any emergency work.
The Claims Process, Step by Step
- File promptly: contact your insurer as soon as practical. Policies have reporting deadlines.
- Get a claim number and the name of your assigned adjuster.
- Meet the adjuster: walk the property with them and point out all damage you documented. Having a contractor present can help ensure nothing is missed.
- Review the estimate: the insurer's scope of work should reflect the actual damage. Ask questions about anything that seems incomplete.
- Choose your contractor: you are generally free to hire your own contractor — you do not have to use the insurer's suggestions.
- Keep records: save every email, estimate, receipt, and photo in one place until the claim closes.
Working With Contractors on Claims
A contractor experienced with insurance work can document damage in the language adjusters use, provide line-item estimates matching the scope, and perform repairs to manufacturer specifications. Be cautious of anyone who offers to "handle everything" for a signed assignment of benefits without explaining it, pressures you to sign immediately, or asks for large upfront payments. Reputable contractors explain the process and let you decide.
Also understand depreciation and deductibles: many policies pay actual cash value first (replacement cost minus depreciation) and release the remainder once repairs are complete. Your deductible applies regardless.
Frequently Asked Questions
Should I file a claim for minor siding damage?
Compare the repair scope against your deductible. If the damage is close to or below your deductible, paying out of pocket may make more sense than filing a claim that goes on your record.
Will my rates go up if I file?
Possibly, depending on your insurer, claim history, and state regulations. Weather-related claims are sometimes treated differently than liability claims, but there are no guarantees — ask your agent about potential impacts before filing borderline claims.
What if the insurer's estimate seems too low?
You can provide competing contractor estimates and ask for a re-inspection or supplement. Document the discrepancy calmly and in writing; most insurers have an appeal or appraisal process.
How long do I have to file?
Deadlines vary by policy and jurisdiction — some allow a year or more, others much less. File as soon as you discover the damage rather than testing the limit.
Storm damage is stressful enough without navigating the process alone. Washington DC Siding Pros connects homeowners with local siding contractors experienced in documenting storm damage and working through insurance repairs. Call (206) 360-4969 to get connected today.
Ready to Talk Siding?
Call (206) 360-4969 and get connected with a local Washington, DC siding contractor today.
☎ (206) 360-4969